Verified Proof
Recent Client Results
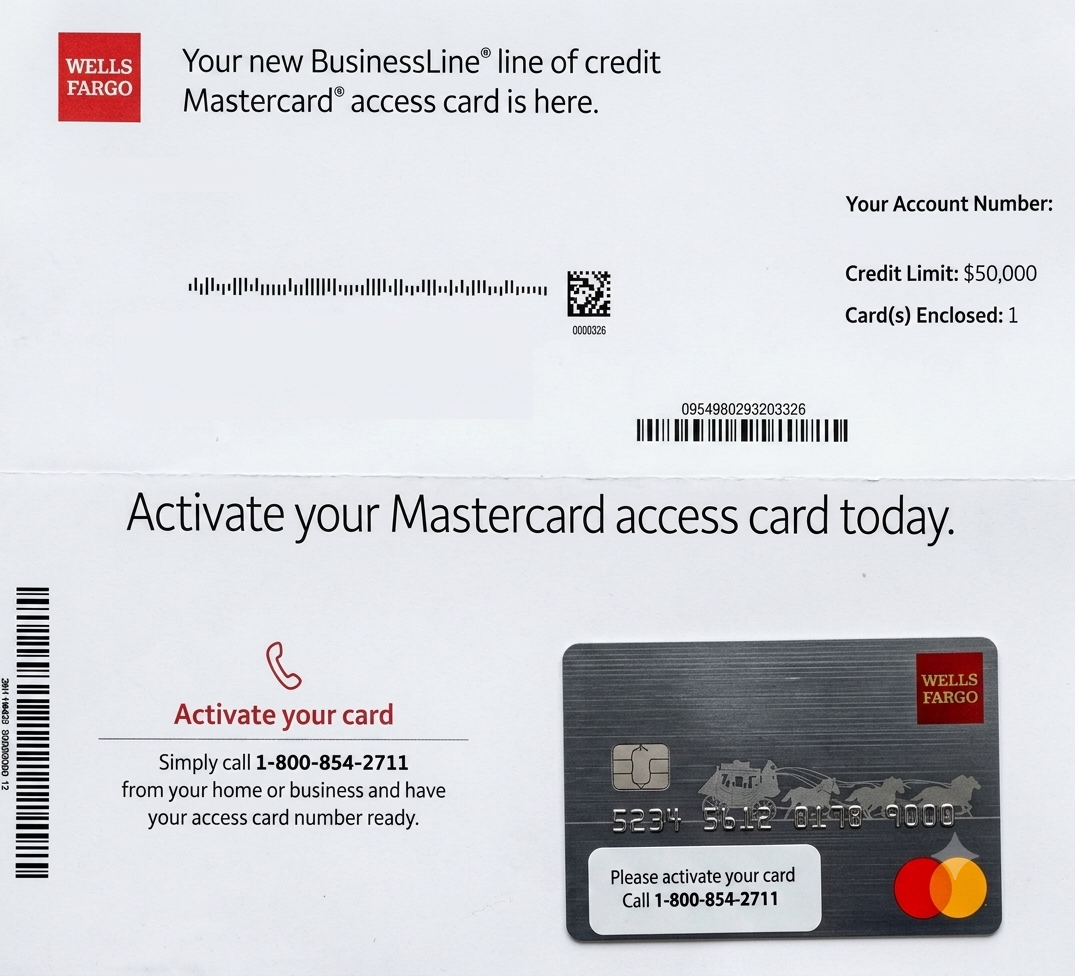
$50,000
Business Line of Credit
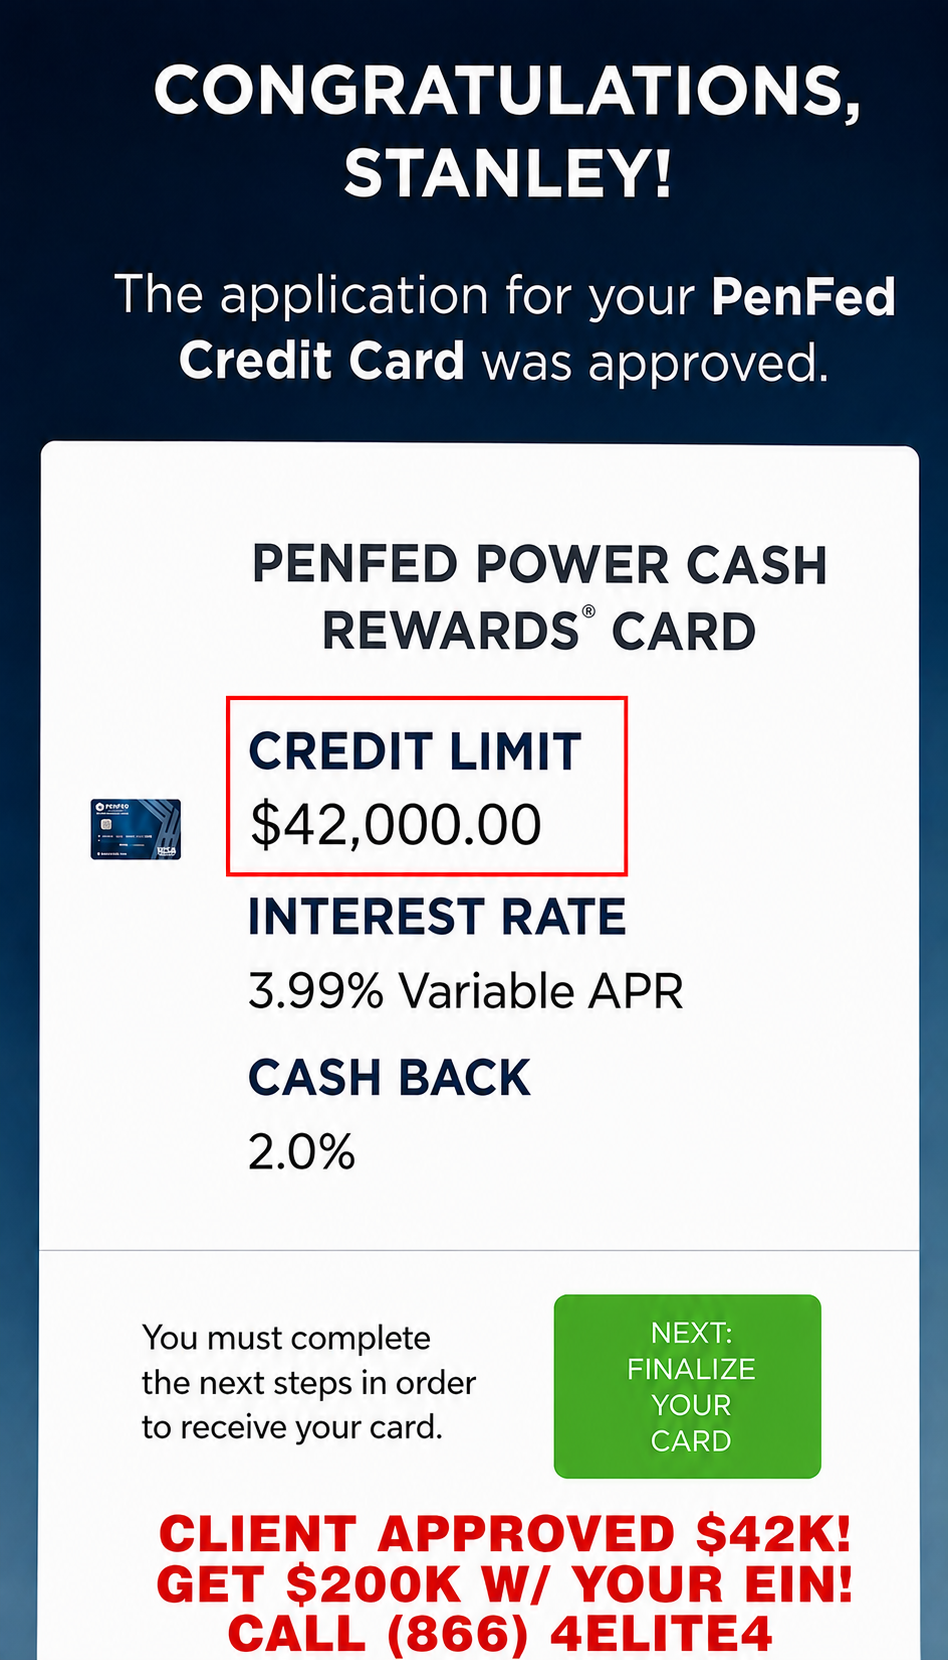
$42,000
PenFed Business Card
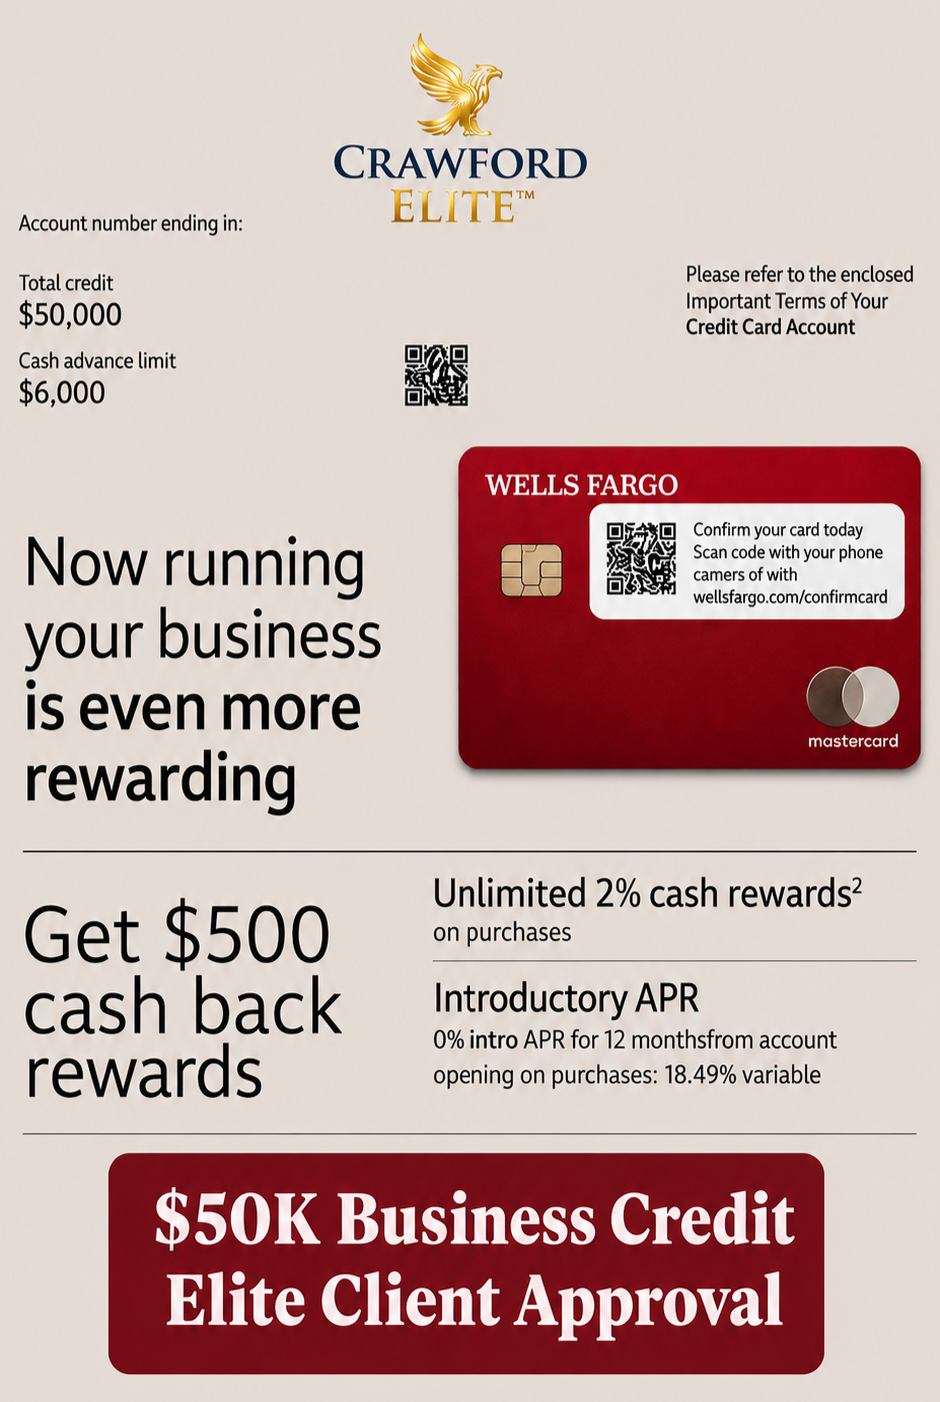
$50,000
Wells Fargo Business Card
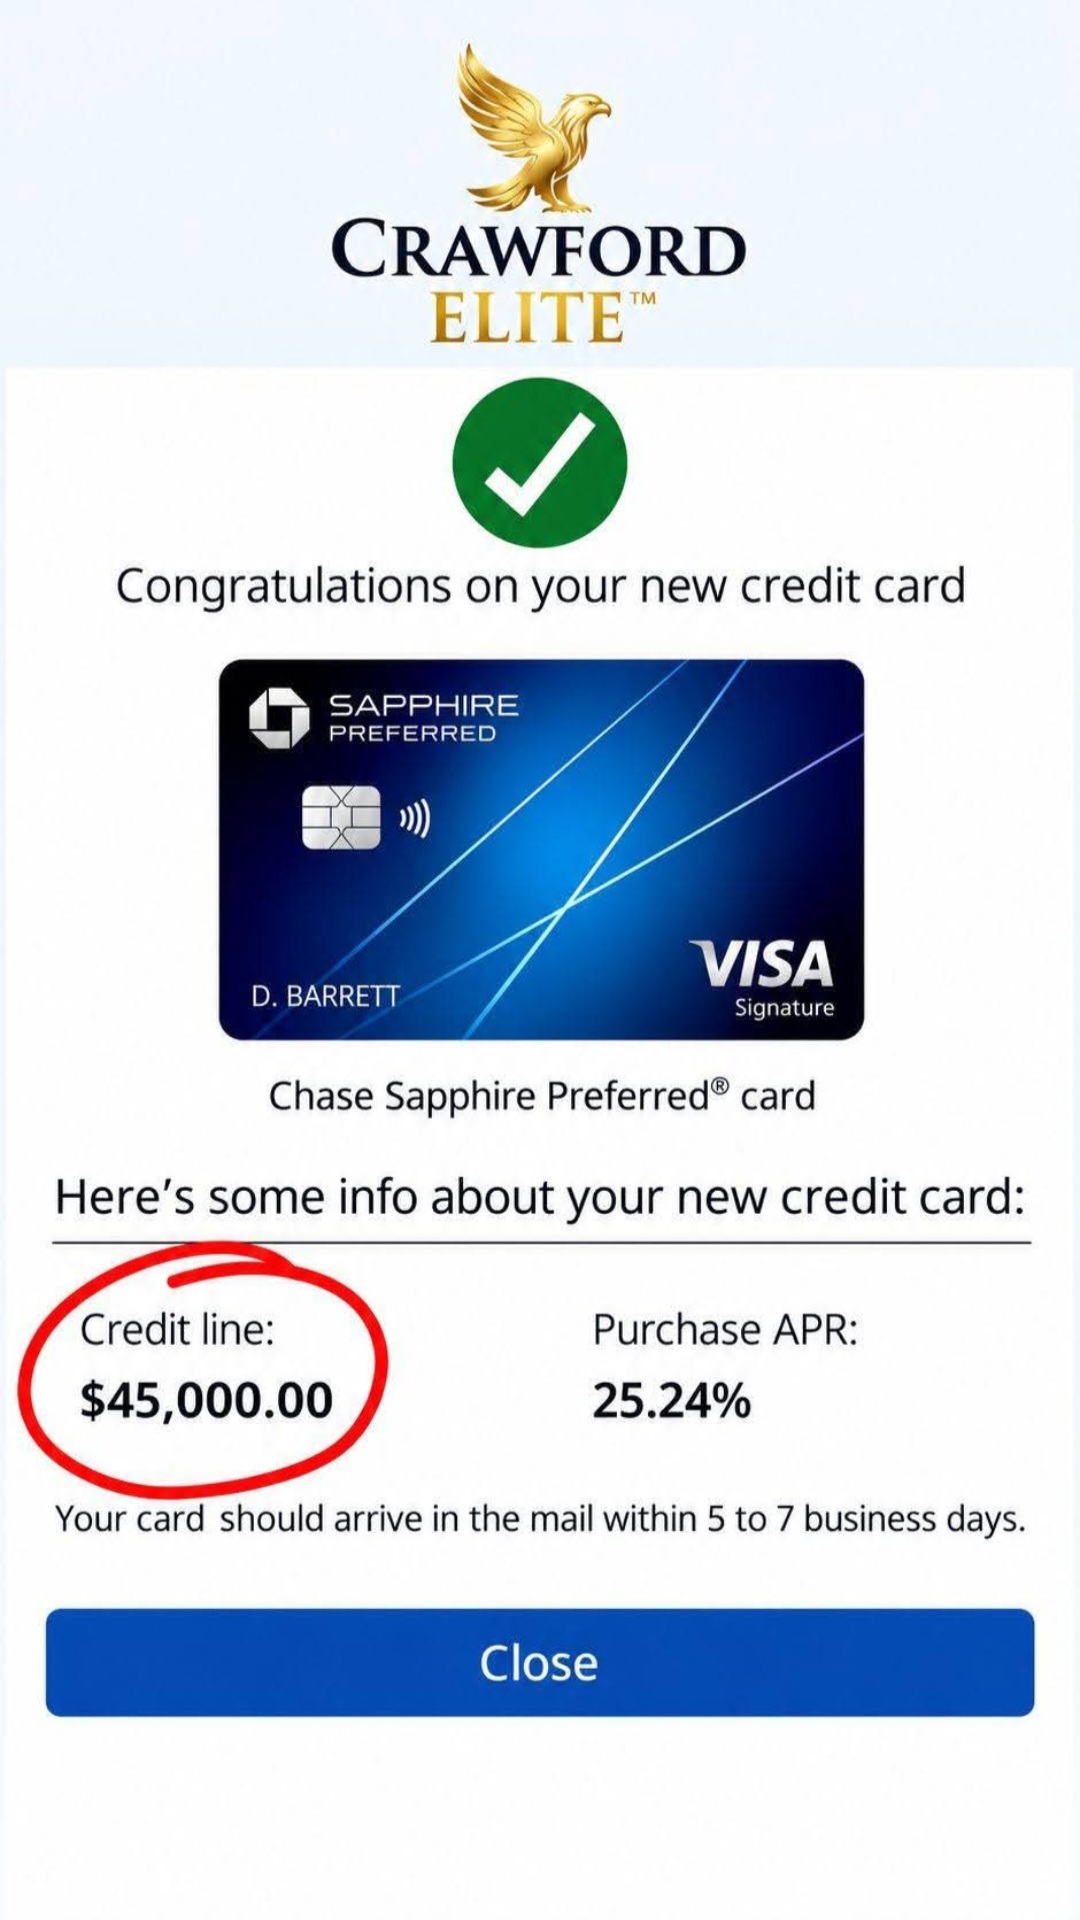
$45,000
Chase Sapphire Preferred
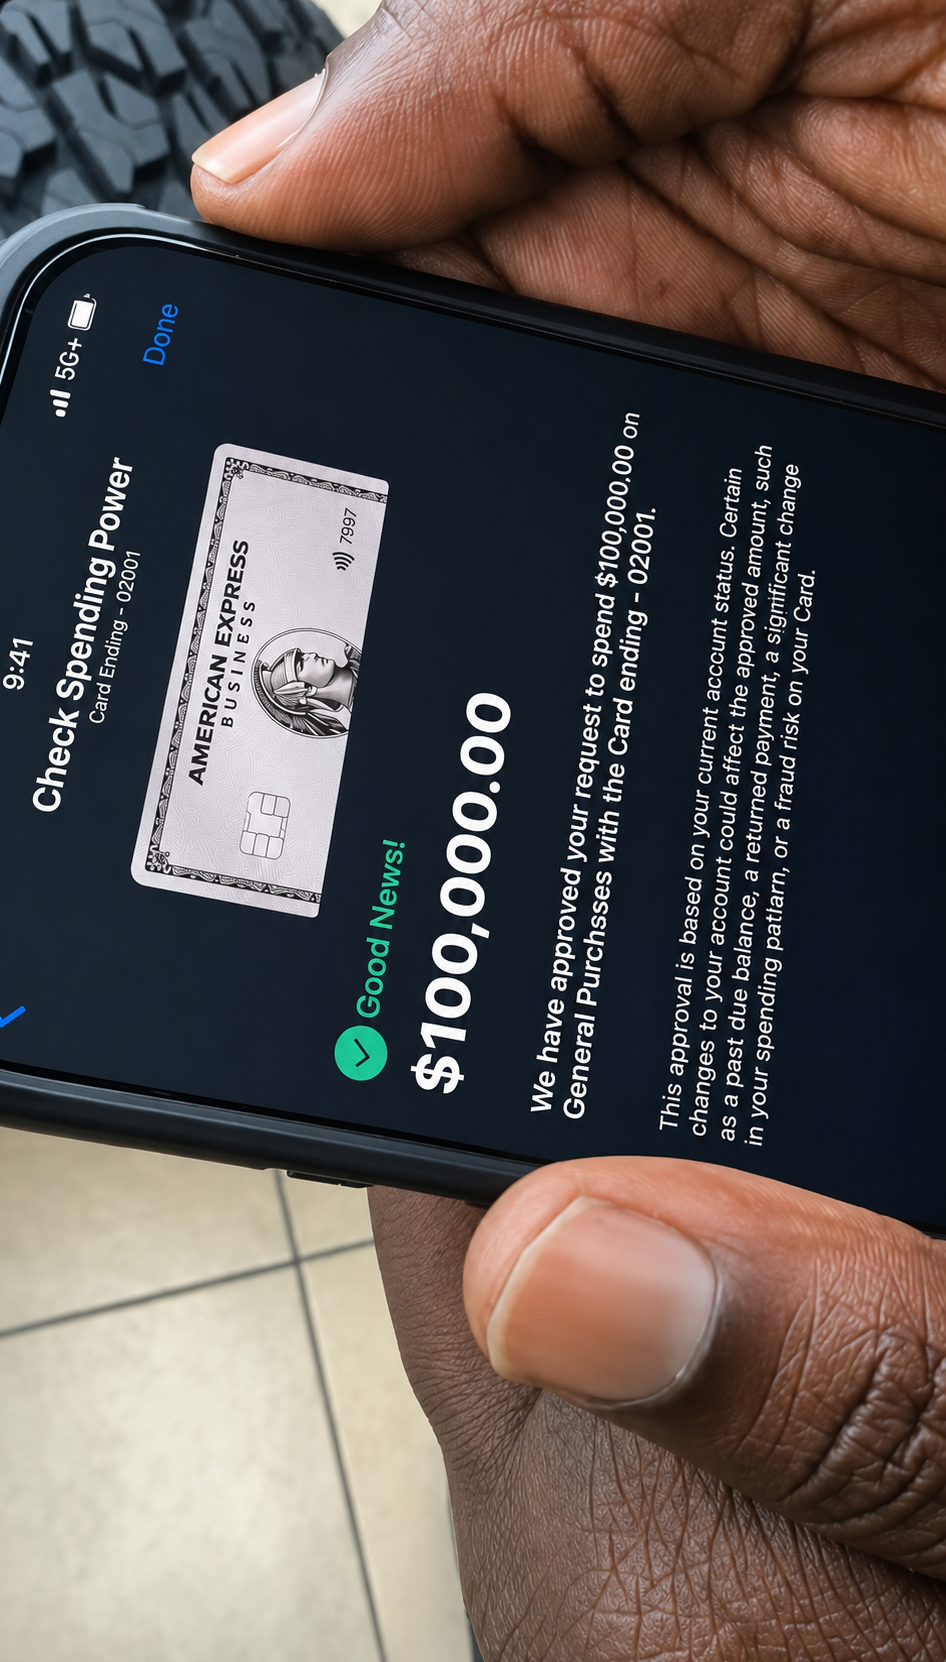
$100,000
American Express Business
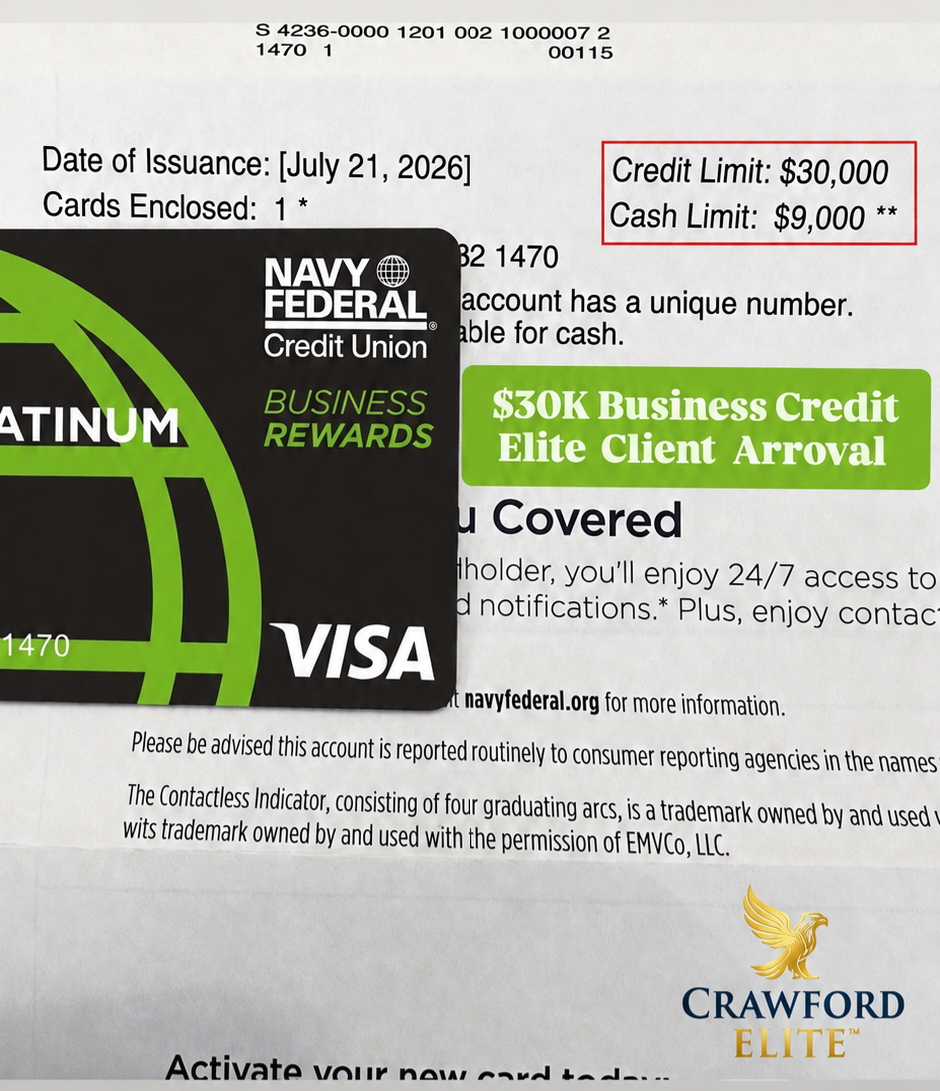
$30,000
Navy Federal Business Platinum
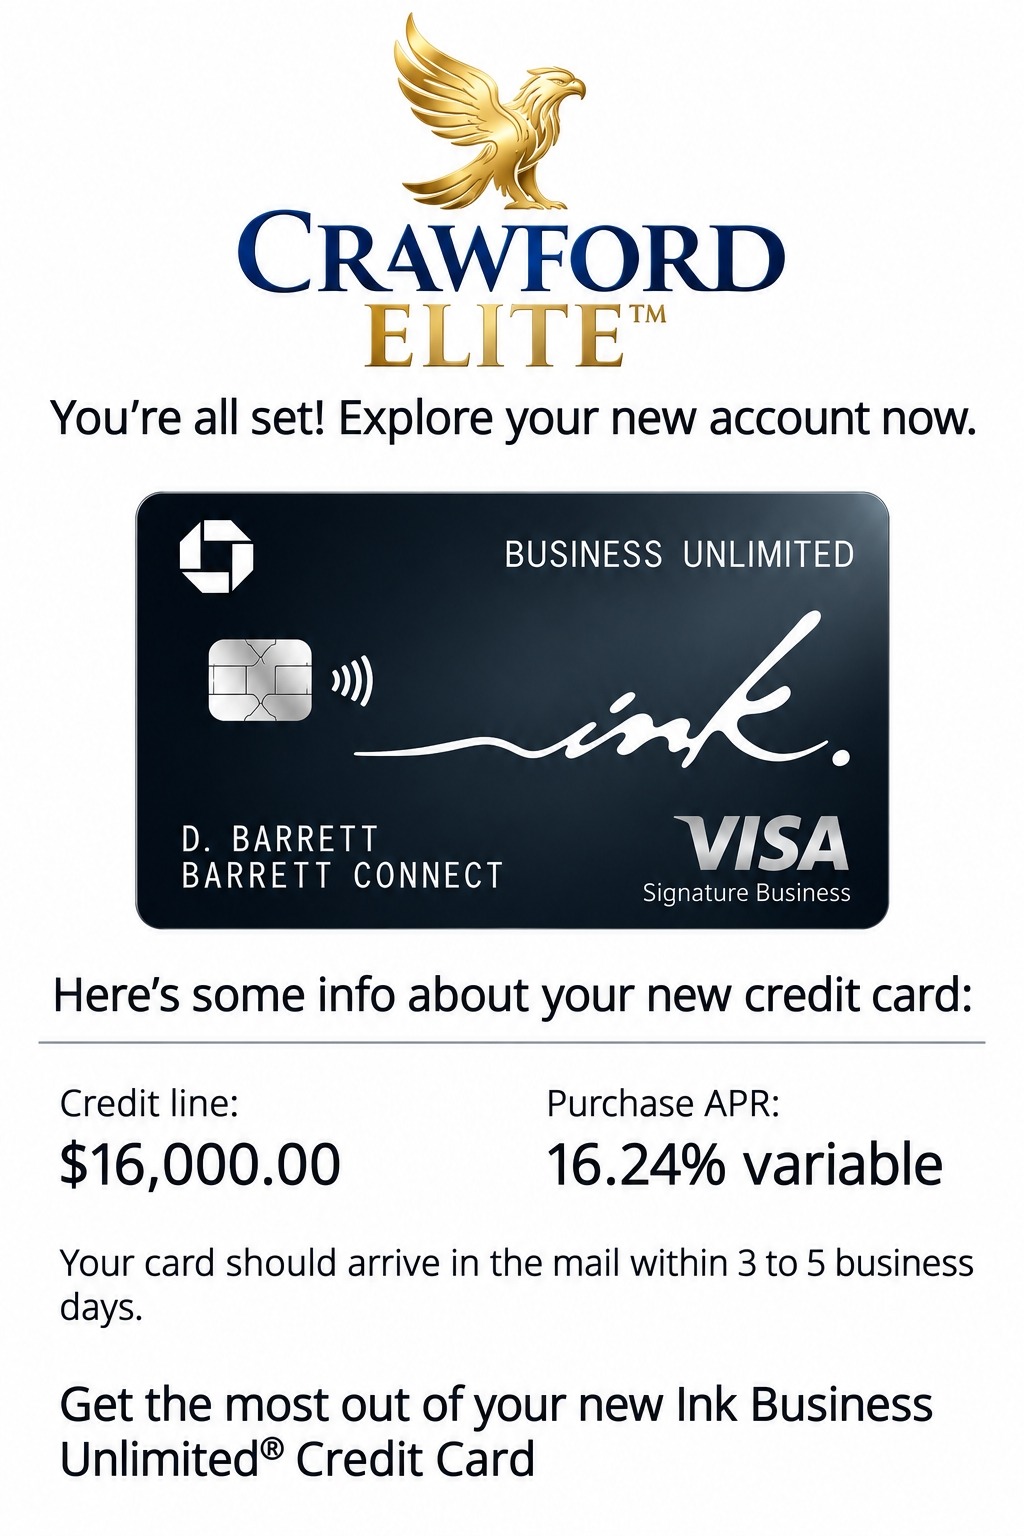
$16,000
Chase Ink Business Unlimited
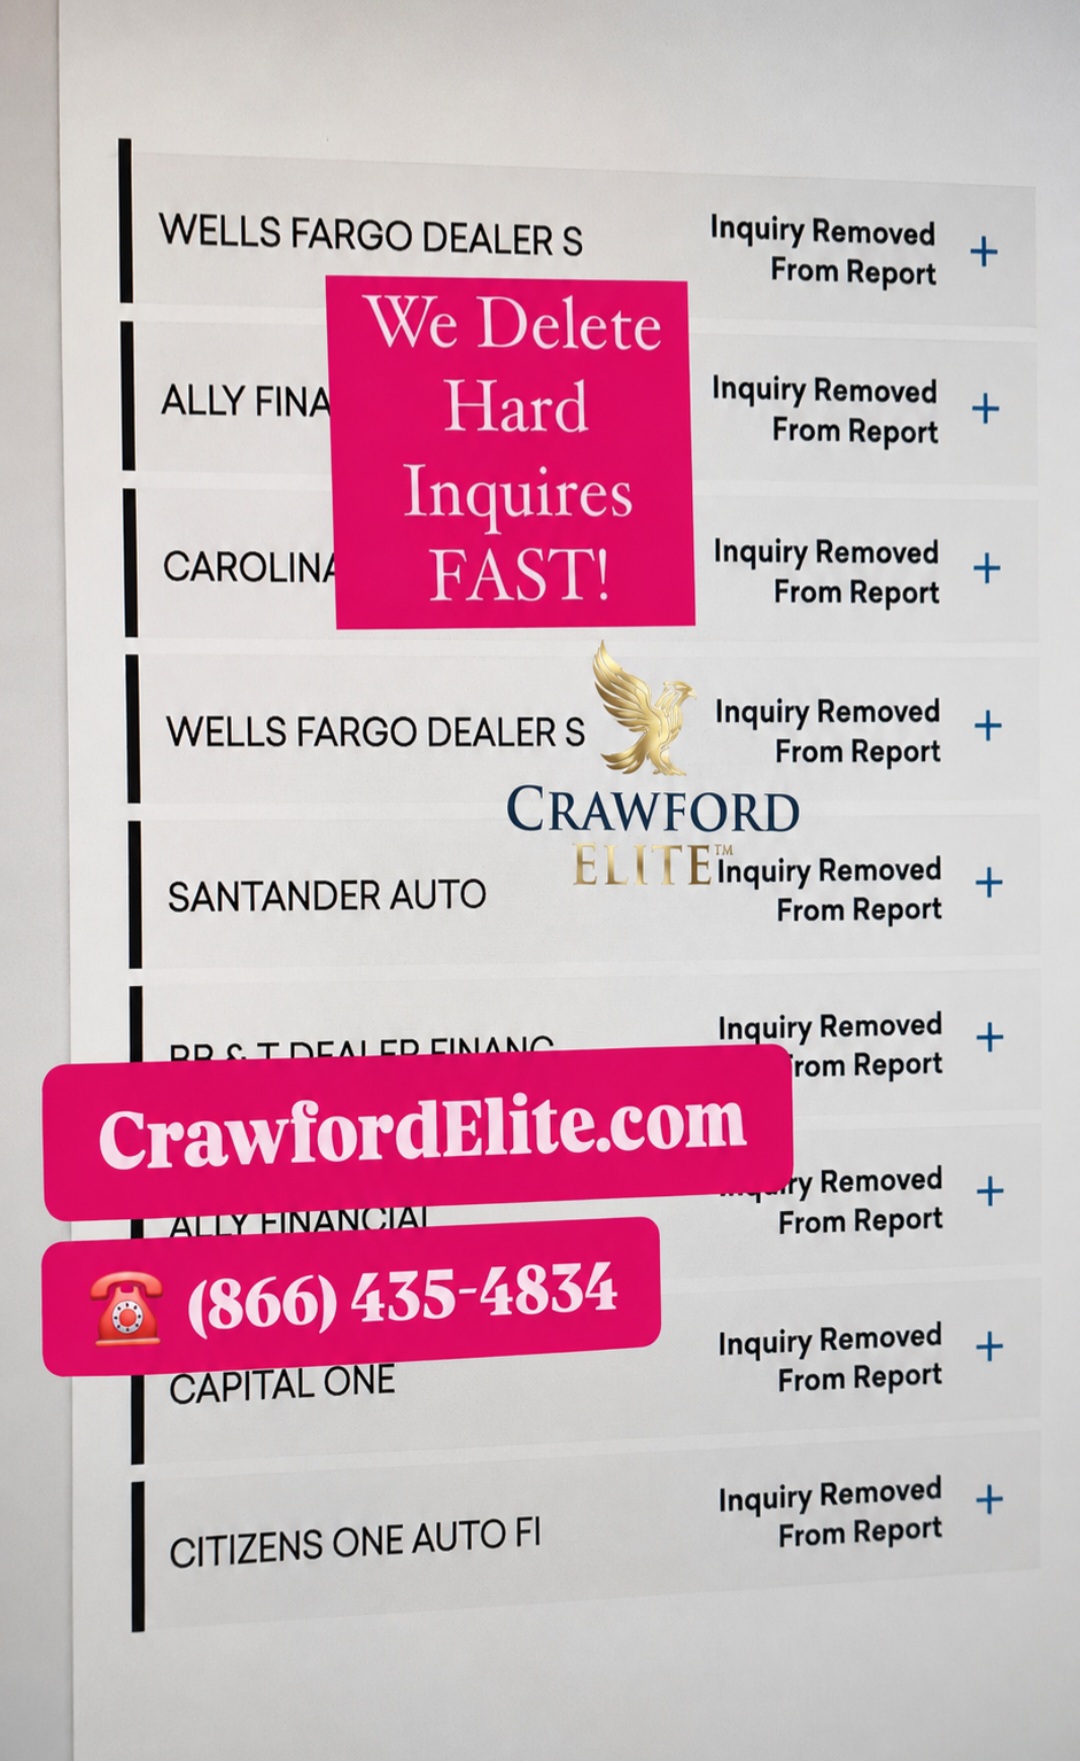
Hard Inquiries Deleted
9 Hard Inquiries Removed
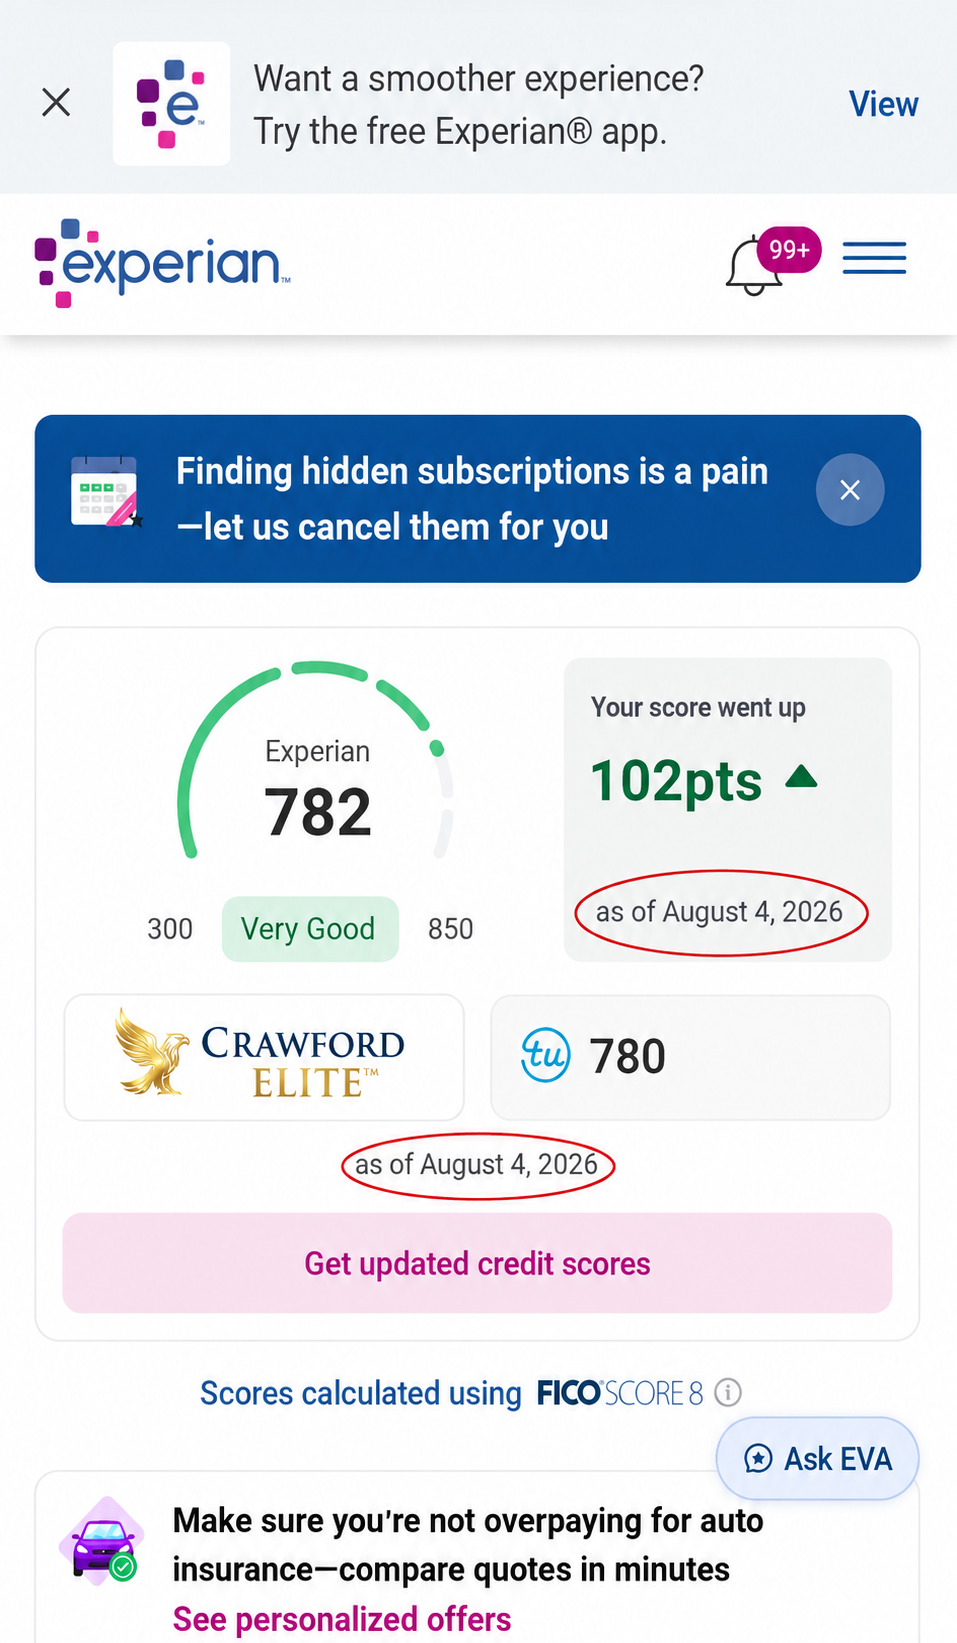
+160 Points
Credit Score Boost Increase
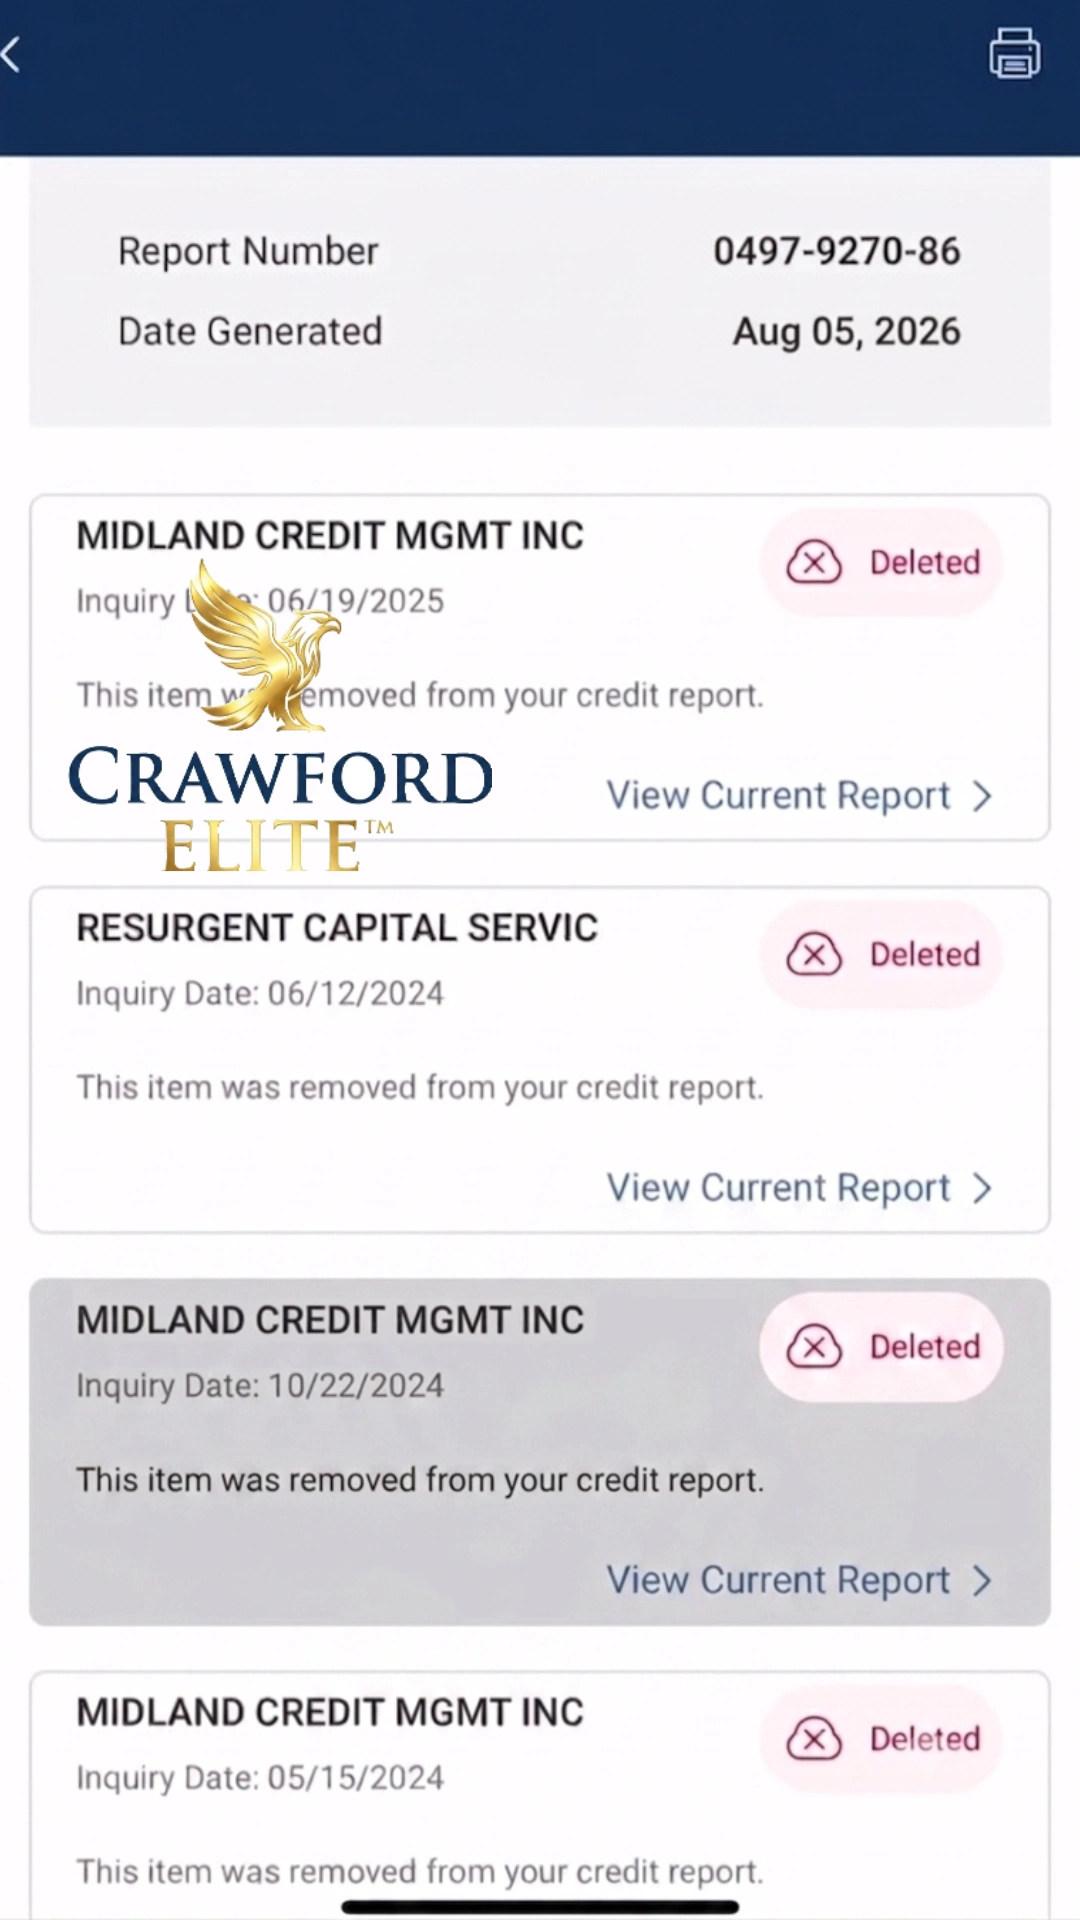
Aggressive Credit Repai
4 Collections Deleted Quickly
What Is Fundability and How Do You Fix It is one of the fastest levers an owner can pull to unlock corporate capital. Here is exactly how Crawford Elite approaches it with our clients.
Why This Matters
Handling what is fundability and how do you fix it correctly is rarely about luck. Lenders and credit issuers run the same checks in the same order, and the businesses that get funded are simply the ones that pass those checks before applying.
At Crawford Elite we build client files in a specific sequence — entity and compliance first, then reporting tradelines, then the approvals. Skipping steps is the single most common reason an owner gets declined with a strong profile.
What Lenders Are Actually Checking
Every underwriter, whether it is a store card issuer or a private lender writing a six-figure line, is answering three questions: is this entity real and verifiable, does it have a payment history someone else already trusted, and can the owner or the revenue support the exposure.
That means a matching EIN, a listed business phone, a real business address, a business bank account with consistent deposits, and reporting tradelines on Dun & Bradstreet, Experian Business, and Equifax Business. When those boxes are checked, approvals stop feeling random.
The Crawford Elite Approach
Our clients run the five-tier path: vendor credit, store credit with issuers like Home Depot, Target, Walmart, Best Buy, Macy's, Saks Fifth, Chevron, Delta and Marriott, then business credit cards, then business cash funding, and finally lines of credit.
The Installment Package builds toward a $200,000 minimum in business credit, fully funded in three to four months, with $3,000 down and $500 biweekly payments toward the $7,000 total. The Platinum Package builds toward a $300,000 minimum in business credit, fully funded in one to two months, with a single $6,500 payment. Neither package includes a shelf corporation — those are purchased separately from our private inventory.
Common Mistakes to Avoid
Applying too early, applying too often, using a residential address on filings, mismatched business names across the Secretary of State, IRS, and bank records, and letting personal derogatories sit unaddressed are the five mistakes that stall the most files.
Fix the profile before the applications go out. Denials leave inquiry footprints that make the next round harder, and rebuilding that momentum costs weeks.
Next Steps
If you want this handled for you, our team audits your entity, your personal profile, and your current reporting, then maps the exact approval order for your business. Most clients start seeing tradelines report within the first 30 days.
Sources & Further Reading
Every claim on this page can be checked against these federal agencies, regulators, credit bureaus, universities, research bodies, banks, and national business publications.
- USPTO — Trademark BasicsProtect the name your credit file is built on.
- FTC — CAN-SPAM Compliance GuideEmail rules for lead nurturing campaigns.
- Federation of Tax Administrators — State Tax AgenciesEvery state's revenue department in one directory.
- TransUnion — Credit FreezeThird-bureau freeze management.
- U.S. Courts — Find a Federal CourtWhere FCRA and FDCPA claims are filed.
- USA.gov — Government Grants and LoansLegitimate federal grant and loan channels, with scam warnings.
- NACHA — ACH Network RulesStandards for electronic payments and returns.
- USAFacts — Government Data ExplorerNon-partisan aggregation of federal economic data.
- Kauffman Foundation — Entrepreneurship ResourcesLeading research on startup capital access.
- Fast Company — Work LifeOperations and leadership reporting.
- IRS — Small Business Tax CenterFederal tax obligations for corporations and LLCs.
- USPS — Business Address Standards LookupStandardize the business address bureaus and issuers try to match.
- FTC — Business Opportunity RuleConsumer-protection rules that surround business purchase claims.
- Capital One — Business Credit CardsSpark card terms and qualification details.
- Macy's CreditRetail account terms for the store tier.
- Office of the Comptroller of the CurrencyPrimary regulator for national banks and their lending.
- SBA — 10 Steps to Start Your BusinessFederal checklist from formation through funding.
- FTC — Advertising and Marketing RulesTruth-in-advertising standards for financial claims.
- Taxpayer Advocate ServiceIndependent IRS help when tax issues block financing.
- AnnualCreditReport.com — Free Consumer ReportsThe only federally authorized source for free Equifax, Experian, and TransUnion reports.
- Cornell LII — Equal Credit Opportunity ActFederal prohibition on credit discrimination.
- SBA — Women's Business CentersLocal federally funded advising for capital readiness.
- PNC — Small BusinessBanking and credit products for small businesses.
- Fed Small Business — Credit Survey ReportsFirm-level data on financing applications and outcomes.
Verify Your Entity in Your Own State
We serve business owners nationwide. Look up filings, name availability, and good-standing status with your state's official business filing office.
- Alabama
- Alaska
- Arizona
- Arkansas
- California
- Colorado
- Connecticut
- Delaware
- District of Columbia
- Florida
- Georgia
- Hawaii
- Idaho
- Illinois
- Indiana
- Iowa
- Kansas
- Kentucky
- Louisiana
- Maine
- Maryland
- Massachusetts
- Michigan
- Minnesota
- Mississippi
- Missouri
- Montana
- Nebraska
- Nevada
- New Hampshire
- New Jersey
- New Mexico
- New York
- North Carolina
- North Dakota
- Ohio
- Oklahoma
- Oregon
- Pennsylvania
- Rhode Island
- South Carolina
- South Dakota
- Tennessee
- Texas
- Utah
- Vermont
- Virginia
- Washington
- West Virginia
- Wisconsin
- Wyoming
More Trusted Reading
Additional national resources for owners building credit, capital, and compliance in any state.
- Consumer Financial Protection BureauRegulator resources, complaint portal, and consumer research.
- MIT OpenCourseWare — EntrepreneurshipUniversity-level coursework, free and citable.
- Investopedia — Business CreditNeutral reference definitions for credit terminology.
- Pew Research CenterIndependent research on household and business finances.
- Navy Federal — Business SolutionsBusiness cards and lines for eligible members.
- Macy's CreditRetail account terms for the store tier.
- CFPB — Small Business Lending Data (1071)The rule bringing transparency to small business lending decisions.
- FDIC — Deposit Insurance for Business AccountsHow coverage applies to corporate and LLC accounts.
- Cornell LII — Uniform Commercial CodeUCC filings and secured-lending fundamentals.
- Federation of Tax Administrators — State Tax AgenciesEvery state's revenue department in one directory.
- SBA — 10 Steps to Start Your BusinessFederal checklist from formation through funding.
- Bing Webmaster ToolsSecond search engine index and diagnostics.
- Dun & Bradstreet — Get a D-U-N-S NumberThe identifier behind the PAYDEX score most vendors and issuers check.
- Experian — Security Freeze CenterManage freezes that can block legitimate underwriting pulls.
- IRS — Business StructuresTax treatment differences between corporations, LLCs, and S-corps.
- FDIC — BankFind SuiteConfirm a lender is a federally insured institution before applying.